Friday, May 30, 2014

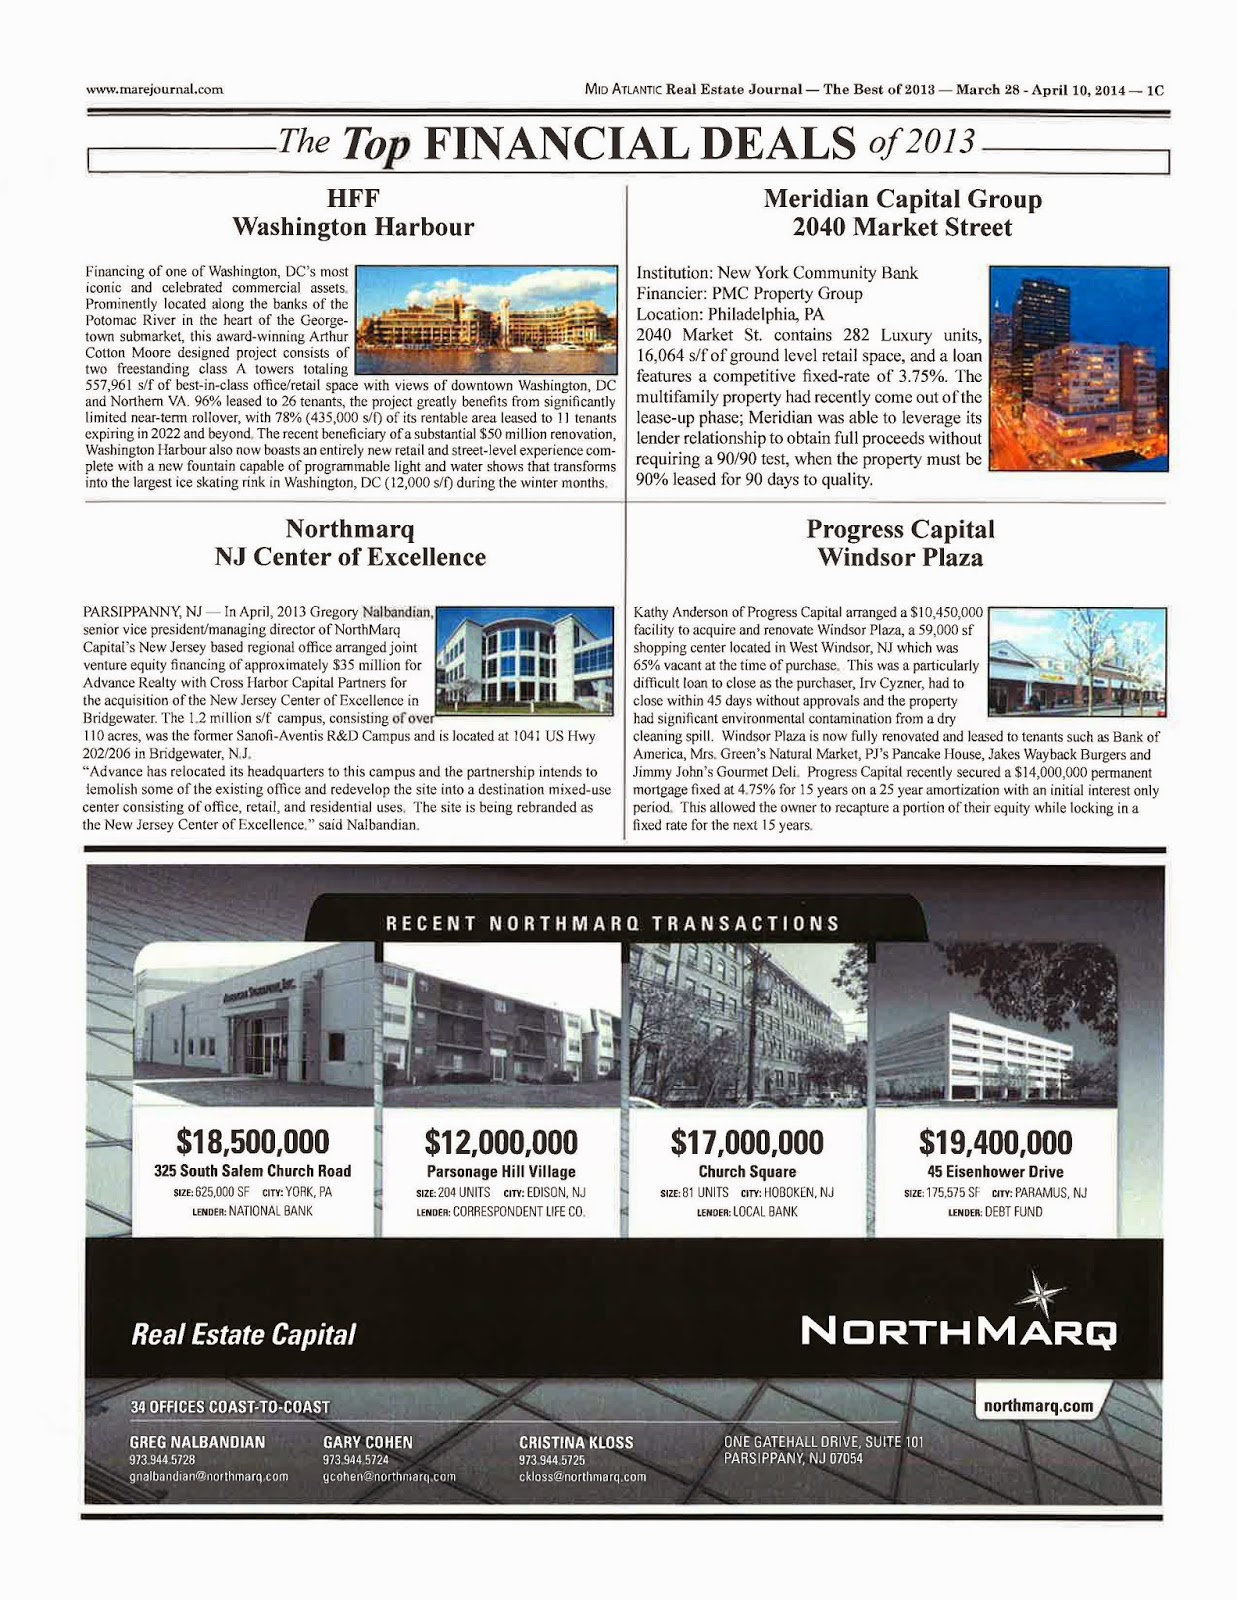
Kathy Anderson arranges financing on Windsor Plaza and is named one of the
 TOP FINANCIAL DEALS OF 2013

Click here >> Read Article

Click here >> Read Article

Progress Capital has been voted as one of the BEST PLACES TO WORK

www.ProgressRealtyAdvisors.com
 
Visit our website at PROGRESSCAPITALADVISORS.com
 

Friday, May 16, 2014

5 Things You Can Do on Friday to Make Monday Awesome


Instead of just waiting for the work week to end, use those few hours and these tips to make next week start out fantastic.


1. Set up some exciting contacts. Spend the afternoon emailing new prospects or perhaps mentors.  Set up a lunch for next week that makes you anticipate good things to come.  People may be slow to reply since its Friday afternoon, but in the worst case you'll come back Monday to some positive responses.

2. Organize the week. Go through next week's calendar and plan out the entire week. Set reminder alarms on your computer or smartphone calendar.  Include all meetings, deadlines, and "to-do" items. Lay out a specific task list with apportioned hours. You'll clear your mind of that nagging feeling that you forgot something and have a truly relaxing weekend, leaving you happier on Monday.

3. Get one thing off your desk. Fridays are the time when it's most tempting to look at projects and tasks and say, "Oh, I'll just pick it back up Monday." So choose one of your ongoing projects and commit to getting it done before you leave. The satisfaction of accomplishment may even motivate you to do more today. And next Monday, you'll have the relief of knowing that task won't be on your desk to taunt you.

4. Shake up your routine. Reflect for a few moments on your usual weekly routine. Make a list of your typical distractions, the habits and stressors that keep you from starting the workweek with a bang. This can be anything from "chatting about the weekend over coffee with officemates" to "reading the accumulated junk e-mail on my laptop" or "hiding from my annoying boss or colleague." Make a list, and then write down what you will do instead. Create a new routine that's uplifting and energizing. Put it where you will see it first thing Monday morning.

5. End the week on a high.  Show your appreciation.  Pick someone in your office that has been extra helpful this week, done a fantastic job on a project, gone above and beyond, or been everyone's ray of sunshine.  Make sure you let them know how much you appreciate their efforts.


Monday, March 31, 2014


Attention:  Co-op Boards
 
Fast Track Early Rate Lock Program Available
  • NYC five boroughs
  • Pricing from 89-95 basis points over 10 Years Treasury
  • Full term I/O available (only 3 basis points add on)
  • Par pricing
  • Up to 12 months forward lock available;  60 day forward no cost
  • Application cost included in spread
  • Good Faith rate lock deposit is 1%
If the Co-op Board is facing a pending maturity of an existing loan over the next year, this programs allows the Board to lock-in a rate for up to 12 months.  The program, also allows up to 10 years of interest only payments if this is of interest to the Board.

For more information contact our office and speak to a loan specialist.


Tuesday, March 25, 2014


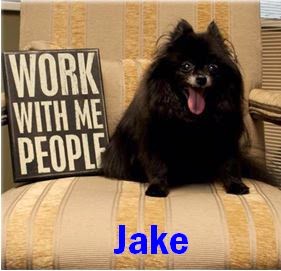
Not all companies are created equal when it comes to the acceptance of dogs in the workplace.  That's certainly not the case with Kathy Anderson, President and Founder of Progress Capital Advisors.  She brings her black Pomeranian, "Jake" to work as often as she can.  The fact remains that some readily welcome your best friend while others have not yet realized the benefits of allowing dogs.
  
Some benefits of bringing your dog to work are: 

- Dogs are frequently recognized as great stress-relievers.

- Often times it is a great ice breaker when a new client comes to the office. Everyone loves talking about their pet.

- What better way to make yourself take a break and clear your head then to take your dog for a short walk. It is proven that frequent short breaks increases productivity.

- A survey of 50 businesses across the US revealed that those with pets had lower absentee rates and employees were more willing to work overtime.


As for Progress, the whole office has adopted Jake and everyone looks after him.  Our clients enjoy seeing Jake and often ask about him.  Since Kathy started bringing Jake to work, we have noticed several other companies in our building have become pet friendly, so it seems like the idea is catching on.


Thursday, February 20, 2014

Why Use A Commercial Mortgage Broker?


If you have ever thought about financing a commercial real estate property, the thought of using a commercial mortgage broker may have crossed your mind.  However, if you are like some people, you may have debated using a commercial mortgage broker based on the belief that it is more expensive to use a broker rather than go directly to a lender. This common belief is a myth.

The reality is that there are a number of ways in which you can save money by engaging a mortgage broker to provide assistance with your commercial real estate financing needs and objectives.  If you take the time to determine the value of using a commercial mortgage broker, you will surely see that it is money well spent.

Locating a Lender  Locating a lender to fund your commercial mortgage is not as easy as it may seem.  Due to the wide range of property types, loan types and special circumstances, a single lender simply cannot offer loan programs for all potential loans.  You may waste a considerable amount of time simply trying to find a lender that offers the program you need.  A qualified and experienced mortgage broker will have multiple lender relationships in place who can offer a wide range of lending options.  Some brokers may even have relationships in place that give you access to hundreds of other lenders offering an unbelievable amount of loan options.

Risks in working with a Single Lender  You may spend the time and locate a single lender that can meet your needs, but you are not out of the woods yet.  By working with a single lender or bank you are putting all your eggs in one basket.  The approval process can take a good deal of time that you may not have.  Then what happens if the loan application is not approved by that lender?  Can you afford to go through the process a second time risking a similar outcome?  By working with a broker, your loan application can be submitted to multiple lenders.  This not only increases the chances that your loan will be funded, but it also gives you and your broker more bargaining power to get the best deal.

Cost Variations between Lenders  One of the most significant ways in which you can save money by using the services of a commercial mortgage broker rests in the fact that there can be notable differences in the interest rates, costs and other fees charged from one lender to the next.  A broker will help you in identifying the most reasonably priced options available from these different mortgage lenders.  On first blush, the cost differences from one lender to another may seem small. But remember, in most instances we are talking about loans in the millions of dollars.  Even if the interest rate difference is minimal on the surface, over time this can add up to a significant amount of money.  Active commercial mortgage brokers are often times provided special rate options based on the volume of business they bring to a lender and this rate savings is passed along to the borrower.

Support Services  Another avenue through which a commercial mortgage broker can help you save money is through their existing relationships with other industry professionals.  A good commercial mortgage broker has a preassembled network of professionals including appraisers, accountants, lawyers and other service providers that they work with on a regular basis.  Not only do you not have to spend the time to find these required resources on your own, but often times you can get a reduced rate on the services due to the brokers existing relationship.  Furthermore, a good commercial mortgage broker will have a staff of professionals to see the loan through to the closing.  Securing a commitment is half the battle.  It takes a village to get to the closing efficiently.

Fees of Commercial Mortgage Brokers  It is true that in the end, you do pay a fee for utilizing the services of a commercial mortgage broker.  However, you will find, as many commercial investors have in the past, that working with a commercial mortgage broker will help ensure that your needs are met and that you get the best deal in the process.  The bottom line is that what you are paying for is a professional on your side, someone to watch out for your best interests.  Similar to the way a lawyer protects your interests in legal matters.  You wouldn't go to court without a lawyer, so don't finance your commercial mortgage without a broker.

A professional commercial mortgage broker will have solid relationships with numerous lenders and will immediately match you up with the best lender based on your needs.  Whether you are in need of a construction loan, long term fixed rate loan or bridge loan, a qualified broker will be able to provide guidance in choosing the best lending source.   If timing is an issue, the broker will be able to leverage their long term relationship with the lender to garner “express” processing of your request.  Everyone needs an advocate at times – a commercial mortgage broker is your advocate in navigating the commercial lending marketplace.


Friday, November 22, 2013

5 Things to Un-learn What You've Learned

You spent a lot of time getting an education. But if you want to make it as an entrepreneur, it's time to forget some of what you learned.

1)     If you only do what you're told, you'll excel.  I know. School was hard.  But not that hard.  If you did what you were told--go to class, do the reading, turn in assignments on time, etc.--you could get As. Initiative was not required and in fact, was often frowned upon.  Now--whether you work for someone else or run your own business--doing what you're told makes you average. Not superior, not excellent... just average.
To be above average or to achieve better than average results, you must do two things
  • Do what others are willing to do and do it better
  • Do what others aren't willing to do
2)     Being micro-managed is to be expected.  Sure, you felt overly-controlled in school: Dates, timelines, rules... not to mention the seemingly arbitrary policies and nonsensical assignments. You saw graduation as the day you would finally have more freedom.  Nope.  In school you paid people to criticize, direct, and at times micro-manage you. Now you're the one getting paid... yet you somehow don't feel it's fair that investors, partners, or customers can dictate what you do, sometimes down to the smallest detail?  Don't expect someone to trust you to perform a task or service–and give you money to perform that service–until you've proven you can be trusted to perform that service.  Then, once you've proven your skills, if you still feel micro-managed it's your responsibility to change the situation. Communicate before you are communicated to. Answer questions before questions are asked. Demonstrate your value before you are asked to prove your value.  No one wants to micro-manage you. They have better things to do with their time.  If you're being micro-managed it's probably because you need to be.

3)     Your time off is the highlight of the year.  You may have forgotten your mom's birthday, but I'll bet you knew the exact day every semester ended and the start and end of Spring Break. And you lived for snow days.  So it only makes sense to see weekends and vacations as the highlight of your working year, right?  Actually, No: If you feel you endure the workweek just to get to the payoff of the weekend, you're in the wrong business. Find work you enjoy; then you won't see time off as a chance to finally do something fun but as a chance to do something else fun.  While you'll never love everything you do in your professional life, you should enjoy the majority of it.  Otherwise you're not living–you're just working.

4)     Getting criticized means you failed.  Here's another pay/paid dichotomy. In college you paid professors to critique your work.  So now that you are the one getting paid, why is it unfair for someone--like a customer, investor, or key partner–to critique your work?  It's not.  When you get negative feedback, see it as an opportunity. Think, "Wow, I didn't realize I wasn't doing that right. I didn't realize I wasn't doing that as well as I could."  Criticism is a chance to learn--and this time you're getting paid to learn.  Never complain when someone pays you to learn.

5)     5. Success is based on toeing the line.  Say you disagreed with a professor's point of view on a particular point. You may even have been right... but the only way to get an A in the class was to parrot the professor's take on the subject. Except in rare cases, confirming and following the rules was everything.  In business, conforming only ensures that you will achieve the same results as other people.  If you want to achieve different results you'll have to think and act differently. Do your homework, think critically, and don't be afraid to create your own path.  But don't be different just for the sake of being different. Be different because it's who you are and what you believe... and because it will get you where you want to go, with your integrity and your sense of self intact


Friday, October 18, 2013

Give Great Feedback: An 11-Step Primer

Star employees aren't born.  They're made by the feedback
they get from bosses and colleagues.

What You Want to Do
  1. Give feedback as quickly as possible.  If someone does something great;  tell them right away.
  2. Go public with positive feedback.  Praise in public is worth more than praise in private.
  3. Be specific.  "Good job" tells your best manager nothing.  "I really liked the accuracy of your report," tells her what she should keep paying attention to. 
  4. Ask questions about what made a meeting, survey, interview or sales call so effective.  Asking questions is a terrifc way to pay a compliment;  it shows you know you can learn from someone else and value that person's perspective.
  5. Inquire about other peoples' contributions.  Who else worked on the project?  This gives the obvious author a chance to share credit and identifies other high achievers you want to notice.
  6. Monitor improvement and progress.  If a group or team is getting a lot better at something, say so.  Everyone likes to feel that they are making headway so ask yourself;  what are these people doing better now that they didn't do a couple of months ago?
What You Don't Want to Do
  1. Overdo your praise.  Make it meaningful, not routine.
  2. Embarass.  Keep negative feedback private and use it sparingly, when it really counts.
  3. Fudge.  Be very detailed and suggest remedies so that you don't inspire hopelessness.
  4. Get stuck in the past.  Suggestions for doing better next time are more motivating than rehashing past events that can't be changed.
  5. Above all:  remember what it was like when you weren't the boss.  What made you want to strive for improvement?  Whether it was a good experience or a bad one, use it--only to do it better for others.

Friday, July 19, 2013

TIPS to Repair Credit & Improve Credit Score


How to repair your credit and improve your FICO credit score
It's important to note that repairing bad credit is a bit like losing weight.  It takes time and there is no quick way to fix a credit score. In fact, out of all of the ways to improve a credit score, quick-fix efforts are the most likely to backfire, so beware of any advice that claims to improve your credit score fast. The best advice for rebuilding credit is to manage it responsibly over time. If you haven't done that, then you need to repair your credit history before you see credit score improvement. The tips below will help you do that. They are divided up into categories based on the data used to calculate your credit score.


3 Important Things You Can Do Right Now

1.   Check Your Credit Report – Credit score repair begins with your credit report. If you haven't already, request a free copy of your credit report and check it for errors. Your credit report contains the data used to calculate your score and it may contain errors. In particular, check to make sure that there are no late payments incorrectly listed for any of your accounts and that the amounts owed for each of your open accounts is correct. If you find errors on any of your reports, dispute them with the credit bureau and reporting agency. 

2.   Setup Payment Reminders – Making your credit payments on time is one of the biggest contributing factors to your credit score. Some banks offer payment reminders through their online banking portals that can send you an email or text message reminding you when a payment is due. You could also consider enrolling in automatic payments through your credit card and loan providers to have payments automatically debited from your bank account, but this only makes the minimum payment on your credit cards and does not help instill a sense of money management.

3.  Reduce the Amount of Debt You Owe – This is easier said than done, but reducing the amount that you owe is going to be a far more satisfying achievement than improving your credit score. The first thing you need to do is stop using your credit cards. Use your credit report to make a list of all of your accounts and then go online or check recent statements to determine how much you owe on each account and what interest rate they are charging you. Come up with a payment plan that puts most of your available budget for debt payments towards the highest interest cards first, while maintaining minimum payments on your other accounts.


Some more tips on how to raise your credit score and maintain good credit

Payment History
Contributing 35% to your score calculation, this category has the greatest effect on improving your score, but past problems like missed or late payments are not easily fixed.
  • Pay your bills on time. Delinquent payments, even if only a few days late and collections can have a major negative impact on your FICO score.
  • If you have missed payments, get current and stay current. The longer you pay your bills on time after being late, the more your FICO score should increase. Older credit problems count for less, so poor credit performance won't haunt you forever. The impact of past credit problems on your FICO score fades as time passes and as recent good payment patterns show up on your credit report. And good FICO scores weigh any credit problems against the positive information that says you're managing your credit well.
  • Be aware that paying off a collection account will not remove it from your credit report.  It will stay on your report for seven years.
  • If you are having trouble making ends meet, contact your creditors or see a legitimate credit counselor.  This won't rebuild your credit score immediately, but if you can begin to manage your credit and pay on time, your score should increase over time. And seeking assistance from a credit counseling service will not hurt your FICO score.
Amounts Owed
This category contributes 30% to your score's calculation and can be easier to clean up than payment history, but that requires financial discipline and understanding the tips below.
  • Keep balances low on credit cards and other "revolving credit".  High outstanding debt can affect a credit score.
  • Pay off debt rather than moving it around.  The most effective way to improve your credit score in this area is by paying down your revolving (credit cards) debt. In fact, owing the same amount but having fewer open accounts may lower your score.
  • Don't close unused credit cards as a short-term strategy to raise your score.
  • Don't open a number of new credit cards that you don't need, just to increase your available credit.  This approach could backfire and actually lower your credit score.

Length of Credit History
If you have been managing credit for a short time, don't open a lot of new accounts too rapidly.  New accounts will lower your average account age, which will have a larger effect on your score if you don't have a lot of other credit information. Also, rapid account buildup can look risky if you are a new credit user.

New Credit
  • Do your rate shopping for a given loan within a focused period of time. FICO scores distinguish between a search for a single loan and a search for many new credit lines, in part by the length of time over which inquiries occur.
  • Re-establish your credit history if you have had problems.  Opening new accounts responsibly and paying them off on time will raise your credit score in the long term.
  • Note that it's OK to request and check your own credit report.  This won't affect your score, as long as you order your credit report directly from the credit reporting agency or through an organization authorized to provide credit reports to consumers.

Types of Credit Use
  • Apply for and open new credit accounts only as needed.  Don't open accounts just to have a better credit mix – it probably won't raise your credit score.
  • Have credit cards – but manage them responsibly.  In general, having credit cards and installment loans (and paying timely payments) will rebuild your credit score. Someone with no credit cards, for example, tends to be higher risk than someone who has managed credit cards responsibly.
  • Note that closing an account doesn't make it go away.  A closed account will still show up on your credit report, and may be considered by the score.
To summarize, "fixing" a credit score is more about fixing errors in your credit history (if they exist) and then following the guidelines above to maintain consistent, good credit history. Raising your score after a poor mark on your report or building credit for the first time will take patience and discipline.